
Tracking day-to-day transactions keeps every small business running reliably.
Proper bookkeeping provides the organized framework your business needs to record them consistently. If you run a company, you depend on that structure. In this guide, we explain what is bookkeeping (if you’re wondering what does bookkeeping mean in practice) and show how the entire workflow operates from start to finish.
Understanding What Is Bookkeeping and Its Purpose
Regular trading activity throws off a steady stream of sales, daily buys, customer receipts, and payments. Systematic bookkeeping keeps these raw financial records accurate and current to back your daily operations. Log every single receipt to guide your practical choices. Paper ledgers are gone, but you still must keep proper records for tax reporting. Modern businesses run on software as the primary tool to handle that recordkeeping workflow.
Good bookkeeping tackles two primary goals across your trade. First, you record every financial transaction accurately by following standard best practices. Second, you calculate and review the financial results of that commercial work.
Bookkeepers sort each operational cost into the right accounts. If you pay for supplies, team wages, or business taxes, they log every transaction. To help owners check financial standing, bookkeepers generate key reports, including the balance sheet and income statement, showing how the business actually performs.
What Does Bookkeeping Mean in Accounting?
To understand what is bookkeeping in accounting, consider a restaurant kitchen: the bookkeeper preps the ingredients. Once you supply what is needed for a recipe, your accountant cooks the meal. That chef then relies on those prepared items to judge the final result.
Bookkeeping
Day-to-day transaction tracking forms the classic heart of Bookkeeping. Under older setups, if you produced raw financial figures, bookkeepers mostly collected and checked quality before opening formal ledgers. Prioritise logging money moving in and out across your everyday accounts. Office admin stays routine, but you still handle regular payroll runs. The workload revolves around administrative tasks, driven by the goal of keeping company records accurate and current.
Accounting
Taking the numbers put together by bookkeepers to interpret, analyze, and summarize them is the actual remit of Accounting. When businesses rely on these structured reports, they see overall performance and establish how much tax they owe. Always check compiled records to judge overall financial health. An accountant may tackle audits, but you still need to prepare formal tax returns. Moving into accounting generally needs more training and study than bookkeeping, making it a natural progression for a financial career.
A Bookkeeper’s Responsibilities
A clear grasp of what are bookkeeping duties protects your daily financial health. You will spot bookkeepers working in full-time corporate jobs, freelancing for plenty of different clients, or managing a side hustle. Make sure you track these key operational responsibilities across your normal working schedule. Anyone working in the role regularly handles several core duties to keep business accounts completely accurate:
- Maintaining the general ledger: In-and-out transactions are recorded by hand or entered into computer systems. Balancing sums preserves accuracy. Through this ledger data, bookkeepers also identify clerical errors and spot fraudulent activity.
- Designing spreadsheets: Spreadsheets provide the primary structure bookkeepers rely on to log data, perform calculations, and review transactions. The role requires knowing how to create, adjust, and apply spreadsheets (leaning on dedicated tools to boost speed and accuracy). Being proficient with spreadsheet software is also beneficial.
- Completing financial reporting: Bookkeepers prepare financial statements and assemble regular reports that guide daily business operations, evaluate performance, and assist management with major decisions. The three standard statements a bookkeeper regularly maintains are the balance sheet, income statement, and statement of cash flow.
- Handling accounts receivable, accounts payable, and payroll: Within small enterprises, these three areas represent the core financial workflow. Day-to-day execution includes issuing invoices and collecting overdue balances. Handling these workflows also covers paying vendor bills and withholding payroll taxes.
- Providing wider operational and advisory support: Across routine operations, transactions are condensed into summary reports that show the health of the company. A bookkeeper’s scope can expand to billing clients, paying suppliers, and working on tax filings. Advisory work also includes tracking key performance indicators and offering strategic advice.
The Bookkeeping Process Step-by-Step
Turn raw transaction logs into clear, dependable summaries by mastering how to bookkeeping. If your paperwork has gaps, you can’t build accurate financial statements later on. Every single transaction needs fresh, up-to-date records right from day one.
Recording Daily Transactions
Daily bookkeeping always begins at the checkout counter. When your registers or POS systems log activity in real time, your business secures a solid financial record. Make sure you log sales, payments, customer refunds, and receipts straight away. Getting that data down immediately gives business owners direct visibility over cash flow right from the start.
You or your bookkeeper post every transaction straight from original source documents. Stashing vendor bills and supplier invoices proves that an actual transaction took place. That trail of paper also covers customer receipts, purchase orders, credit memos, and related files, all matched to your chosen accounting method.
Posting to Journals and Ledgers
Fresh records enter accounting journals strictly in the order they happen. Known formally as books of original entry, these logs capture initial business activity first. Once you start posting, you transfer those journal entries over to specific ledger accounts. That process groups cash, revenue, liabilities, and operating expenses by individual account balance.
Performing a Trial Balance
The trial balance lets bookkeepers test mathematical accuracy across every ledger account. When you list out each account, debit totals must match credit totals dollar for dollar to keep figures straight. Sort out any arithmetic errors before building your final financial statements. A balanced sheet catches calculation faults, but it won’t uncover every hidden recordkeeping mistake.
Preparing Financial Statements
This final stage requires pulling together the balance sheet, the income statement, the cash flow statement, and accompanying disclosures. Putting these reports together gives you the factual foundation you need for compliance. They reflect your overall financial health and operational performance, giving you the facts to guide performance analysis and smart business choices.
Key Bookkeeping Definitions and Terminology
Grasping what is bookkeeping rests on a handful of basic ground rules and core terms. If you keep financial records, these simple concepts guide your day-to-day workflow.
Journals and Ledgers
The general ledger holds every single transaction your company makes, sorted neatly into specific accounts to build your complete financial history. Everything you post stays filed by category inside this master log.
Chart of Accounts
Every category you use to log financial activity sits in a master list called the chart of accounts. These buckets, formally called general ledger codes, give each incoming or outgoing transaction a clear home.
Think of the chart of accounts as a table of contents for your business finances. Instead of digging through line items, you glance at this index to find major sections running from Sales Revenue all the way to Office Supplies.
Assets, Liabilities, and Equity
Every company balance sheet rests on three main categories 👇
- Assets: Any resource owned outright or held in part by a company qualifies as an asset, with examples including machinery, commercial property, product inventory, and customer balances owed under accounts receivable.
- Liabilities: Any financial obligation or outstanding debt a business must pay, with examples including unpaid vendor bills, employee wages, business taxes, and commercial bank loans.
- Equity: The total financial stake that owners or investors retain in the company, consisting of capital contributed or taken out, alongside accumulated retained earnings.
Revenue and Expenses
Revenue
Your overall earnings roll in from customer sales, earned interest, shareholder dividends, and other incoming payments.
Expenses
Keeping daily operations running needs regular spending. Typical costs include things like building rent, staff wages, office supplies, and everyday utility charges.
Financial Statements
Balance sheet
This report lists your assets and liabilities together. Checking it gives you a clean snapshot of exactly what your business owns and owes on a single date.
Profit and loss (P&L) statement
Measured across a defined timeframe, this summary matches your revenue against operating expenses to reveal your true profitability and operating performance.
Journal Entry
Your books log every single financial event through a journal entry. That record names the specific accounts involved alongside their exact debit and credit values.
Bookkeeping Methods
Pick an accounting framework that fits operational scale, daily transaction volume, and incoming cash flow. Settle this choice before you log daily entries.
Single-Entry Bookkeeping
Overview
Under single-entry bookkeeping, each financial event takes up just one row. You simply log every transaction once as incoming revenue or an outgoing expense.
Best For
Sole traders, brand-new startups, and small outfits with straightforward activity usually pick this single-entry format. If you run basic operations, keeping things simple makes sense. Just remember this ledger cannot produce a complete financial view or support detailed analysis.
Running this setup means keeping three core financial records 👇
- Cash sales journal: The designated log where an owner enters all business revenue.
- Cash disbursements journal: The designated log where an owner enters every company expense.
- Bank statements: External bank account records against which every recorded entry must reconcile.
Double-Entry Bookkeeping
Overview
Double-entry bookkeeping logs every transaction twice across at least two separate accounts. This process creates balanced debit and credit entries across two or more accounts in your general ledger.
Accounting rules rest on a simple fact: money never appears or vanishes on its own. Every financial move has two sides that balance out. When money leaves one account as a credit, you post it to another destination as a debit. That offsetting system keeps books balanced, and the offsetting structure causes data entry mistakes to surface immediately.
Best For
Accrued expenses definitely make the double-entry setup more complex. If your business is growing, you’ll want this framework to spot recording errors early. Established firms rely on it for an accurate summary of expenses, income, liabilities, and assets.
A standard equipment buy shows how dual entries work. When Printing Plus buys $3,500 of operating gear on January 5, 2019, terms call for payment within thirty days. Your bookkeeper debits the Equipment asset account. Stockholders’ equity stays untouched at $0, but you still credit Accounts Payable liabilities. By balancing debits against credits, this entry increases liabilities and assets while fully protecting what’s known as the basic accounting equation.
Cash vs. Accrual Basis
Cash Method
With the cash method, you log transactions only when money actually leaves or enters your account. That straightforward standard keeps daily tracking simple and direct.
Accrual Method
The accrual method tracks commercial activity right when it happens. If costs occur, your bookkeeper records operational expenses straight away. You enter incoming revenue once earned, without waiting for cash to change hands. Accrual accounting is more complex, but it delivers a complete picture of operational performance for formal reporting across larger businesses.
Say you finish client work in December and the invoice clears in January. If you use cash accounting, you log that customer payment in January after payment clears the bank. Accrual accounting books that revenue back in December, matching your actual monthly operating output.
Businesses decide between these two frameworks along two distinct paths:
- Stick with Cash Basis if: You operate as a freelancer, sole proprietor, or service business without physical stock, remain beneath legal tax revenue limits, and prefer simple records aligned with your cash balance.
- Switch to Accrual Basis if: You hold physical merchandise inventory, offer Net-30 or extended credit terms to clients, plan to seek bank financing or outside capital, or pass statutory revenue caps set by tax authorities.
Why Good Bookkeeping Is Crucial for Your Business
Clean financial records give you the foundation to steer your business with confidence. When you keep your books organized, mapping future plans doesn’t feel complicated. Spotting fresh commercial opportunities gets easier too, while meeting your mandatory filing duties on time prevents costly compliance errors. Log every business receipt to protect your long-term commercial stability. Tidy books keep your business healthy and fully prepared for growth.
Accurate Tax Calculation and Filing
Thorough financial records make your tax season obligations much simpler through several direct benefits:
- Working out the exact tax owed and preparing for the upcoming financial year starts with reliable bookkeeping.
- Filing early taxes becomes simpler when records are organized, which guarantees HMRC receives accurate Income Tax and National Insurance information.
- Operating with accurate, well-maintained books keeps a company compliant with the ATO while making the lodgement of activity statements and tax returns straightforward.
- Handling daily bookkeeping duties involves withholding taxes, generating sales invoices, settling vendor bills, and collecting on past-due accounts.
- Producing accounting reports shows the financial performance of the enterprise and establishes the exact amount of tax owed.
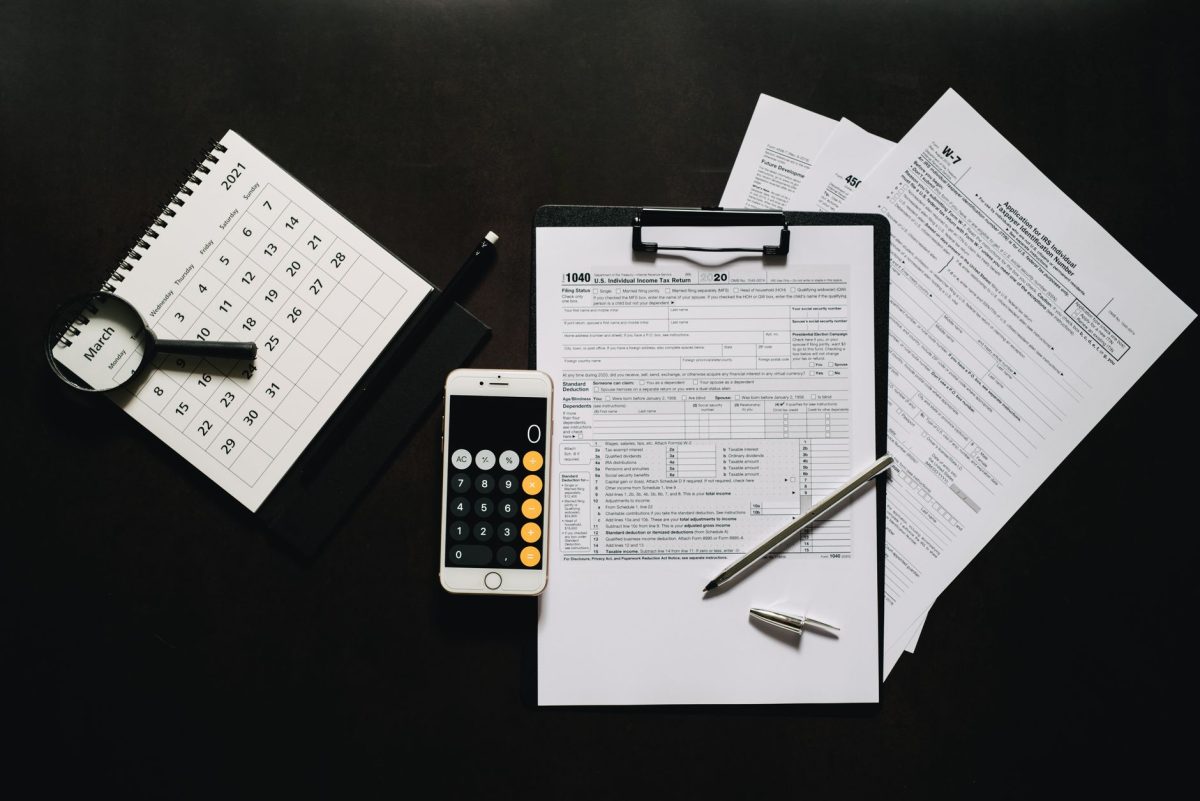
Consistent day-to-day bookkeeping feeds right into Schedule C. That schedule covers your Profit or Loss From Business, Sole Proprietorship, which you file right alongside Form 1040, U.S. Individual Income Tax Return. For Tax Year 2022, exactly 30,983,810 returns reported nonfarm sole proprietorship activity. That marked a 5.7% increase from the 29.3 million filed in 2021. Those businesses brought in $2,080.7 billion in total receipts and claimed $1,671.9 billion in deductions. That left $410.7 billion in total net profits. Sole proprietors bringing in $100,000 or less made up 88.7% of those filers. Even so, they accounted for only 30.1% of all reported profit. Every single tracked dollar counts. Remember, the simplified Schedule C-EZ was eliminated starting in Tax Year 2019 under the Tax Cuts and Jobs Act. You need clean books throughout the entire year to capture every allowable write-off. If you claim asset depreciation, report it on Form 4562. Account for farm income on Schedule F, and itemize personal deductions on Schedule A. Make sure to track the home office deduction on Form 8829, or claim the simplified method on Schedule C at $5 per square foot, up to 300 square feet.
Better Financial Decision-Making
Accurate financial reporting gives business owners the clear visibility needed to guide company growth across several areas:
- Managing monthly cash flow, paying vendors, purchasing inventory, and keeping up with tax payments all require books that stay up to date.
- Catching problems early and making smarter business choices come from remaining organized.
- Giving advice on business structure, tax efficiency, owner compensation, and potential VAT registration requires strong bookkeeping data that accountants can trust.
- Deciding whether to expand current operations or incorporate as a limited company depends directly on these financial records.
Clear Data for Your Accountant
Accountants still need organized business records, incoming receipts, and customer invoices from you to finish your accounts properly.
Easier Legal and Compliance
Proper financial recordkeeping helps your business fulfill regulatory mandates and legal reporting standards:
- Filing a Self-assessment return is mandatory for company directors and self-employed individuals, a requirement that relies on precise expense and income logs.
- Meeting standard legal requirements set by the Australian Taxation Office (ATO) is mandatory for Australian businesses.
- Lodging official tax returns requires bookkeepers to hold BAS certification.
Best Practices for Small Business Bookkeeping
Consistent bookkeeping habits give you an accurate, live view of your cash flow. Whatever your daily setup looks like, these basic standards apply to every business. Put them into practice to keep your company records spotless.
Keep Business and Personal Finances Separate
Opening a dedicated business bank account cuts out messy confusion right away. Splitting your funds makes tracking income and costs simple. That clean divide gives your trade a clear, professional financial structure.
If you mix personal and business money by accident, sort it out quickly to keep your books clean:
- Personal card used for business: Submit an expense claim with the receipt attached, then transfer the exact reimbursement from the business bank account to your personal account.
- Business card used for personal items: Transfer the exact amount back from personal funds into the business account, categorizing the transaction as an Owner Draw repayment.
- Document the transaction: Add an audit note in your software noting an accidental card swipe and date of repayment.
Update Your Books Regularly
Log transactions every single week rather than letting paperwork pile up on your desk. Doing this stops errors, boosts balance accuracy, and shows your real cash flow. Plus, fresh records make tax deadlines completely painless.
Maintain All Receipts and Supporting Documents
Keep every single receipt, whether you store paper copies or digital scans. If an auditor comes calling or tax deadlines arrive, these documents provide solid proof for every recorded cost. Filing them properly confirms transaction details and makes sure no deductible expense slips through the cracks.
The software tools below offer direct receipt capture and clear entry pricing to keep your paperwork sorted 👇
| Receipt Tool | Starting Pricing | Key Capture Feature |
|---|---|---|
| Zoho Expense | Free (up to 3 users) or $4 per user | Cost-effective entry with an 8.3 out of 10 Consumer Sentiment Index score across 8,071 insights |
| Veryfi | Free | Direct mobile and digital document capture |
| Expensify | $5 per user | Fast mobile receipt scanning |
| TripLog | $5.99 (single user) | Expense and mileage tracking |
| Wave | $8 per user | Built-in receipt management for small business bookkeeping |
| Shoeboxed | $9 per user | Magic Envelope service to mail physical paperwork for on-site scanning and human data verification |
| Rydoo | $12 per user | Direct forwarding of emailed vendor receipts with automated data extraction claiming greater than 95% accuracy |
| Dext | $23.92 per client (10-client minimum) | Automated document collection built for multi-client bookkeeping |
| Intuit QuickBooks Online | $38 | Built-in mobile receipt scanner that syncs data across over 800 platforms |
| Coupa | Custom quote | Enterprise-level spend and expense management |
Gathering paper records never needs to be a painful manual chore. Choosing a dedicated receipt tool speeds up document collection and fits neatly into your normal working routine.
Common Bookkeeping Mistakes to Avoid
Small businesses often run into bookkeeping slip-ups because owners try to handle every task at once. If you make these blunders, you’ll face costly headaches down the road. Protect your business by staying sharp on details and setting up solid habits right away to dodge these pitfalls:
- Mixing personal accounts and business finances
- Failing to keep receipts and supporting documents properly
- Not reconciling your bank statements regularly
- Missing or late recording of business transactions
- Incorrectly categorising your expenses or income
- Neglecting to back up your financial data
- Overlooking outstanding invoices or incoming payments
- Relying on inconsistent bookkeeping methods or software
- Not tracking your petty cash properly
- Ignoring mandatory tax deadlines and compliance requirements
DIY vs. Outsourced Bookkeeping
You rarely face an easy decision when deciding whether to manage the books yourself or hire an expert. When you strip it back, this all depends on two things: your available hours and your practical know-how.
Most founders don’t launch a company just to balance general ledgers every week. Handing that paperwork to an outside specialist gives you the space to refine your business plan and expand operations.
Assessing Your Expertise
Start by checking where your bookkeeping ability stands today. Maybe you took a couple of college classes. Or you’re leaning on a rough grasp of how numbers work while hoping things run smoothly. Even with that background, you might still lack the deeper technical knowledge you need to keep records straight.
Handling your own books gets messy fast. That happens the minute GST rules and local tax codes are unfamiliar to you. Turning those duties over to an outside pro makes sure your records stay accurate. That lets you point your attention straight back to your business.
Assessing Your Time Commitment
Tackling your own numbers is always an option. You just need to block out enough hours to balance your ledgers on a steady schedule. Offloading administrative records gives founders space to concentrate on core operational expansion.
Bookkeeping is slow, detailed grind that eats into your calendar. Early on, you’re already stretched thin just trying to get operations running. Sort out your business bank account, keep debits apart from credits, and lock in steady record-keeping habits first. Adding regular bookkeeping on top of those daily duties can quickly leave you overwhelmed.
A simple rule applies here. Running the books yourself works fine when you have zero employees and very few transactions. That changes the moment payroll enters the picture, sales grow complex, or you need to track inventory. Making an error often costs far more than paying for professional help.
Frequently Asked Questions about Bookkeeping
What are the core ethics of bookkeeping?
Sound bookkeeping hinges on four core ethics, including confidentiality to protect proprietary commercial figures:
- Integrity: Being honest and transparent with financial records.
- Objectivity: Avoiding bias or personal influence in financial reporting.
- Confidentiality: Protecting sensitive financial information.
- Professional Competence: Maintaining accuracy, skill, and up-to-date knowledge.
What is the hardest part of bookkeeping?
Consistency and accuracy across your records form the toughest hurdle here. When transaction numbers spike, categorising costs, balancing accounts, and sorting out mistakes take relentless daily effort. Staying square with tax rules needs serious discipline.
Is bookkeeping easy to learn?
Yes. Beginners pick up the fundamentals fairly fast, but true skill takes hands-on time with real software and guidelines. Nobody needs a university degree to get started. Standard qualifications usually just call for a high school diploma or General Educational Development (GED) certification.
A structured course shows you how to balance ledgers and put together clear financial statements. You’ll want to use tools like Microsoft Excel to keep your numbers clean. From there, learn foundational accounting rules, test popular bookkeeping software, and get fluent with spreadsheets.
Self-paced online training gives you another flexible route to study key bookkeeping and accounting methods. Most businesses search for proven software experience alongside practical know-how, so putting in the hours to teach yourself really helps you stand out.
Understanding what is bookkeeping and treating it as an operational engine turns boring back-office paperwork into genuine insight. Solid ledgers hand you live numbers for making smart calls quickly, well beyond checking off annual tax obligations. If you nail your routine reconciliations and record spending accurately, you shield the whole business from expensive blunders. That firm grip keeps everything running smoothly as your sales volume climbs.
Explore More Topics: